Novated Lease vs Car Loan: Which Is Right for You?
A novated lease is a three-way agreement between you, your employer and a financier, paid from a mix of pre-tax and post-tax salary. A car loan is money you borrow and repay from your take-home pay, and you own the car from settlement. The deciding factor is usually your employment, not the car.
Consider a novated lease if you are a salaried employee, your employer offers salary packaging, and you want running costs bundled into one deduction.
Consider a car loan if you are self-employed, between jobs, on a casual or short-term contract, or you want to own the car from day one.
Either way, compare the total cost over the full term, including fees, the final payment and running costs, rather than only the weekly figure.
Key Takeaways
A novated lease needs an employer. No employer, no novation. That rules it out for most sole traders and contractors.
With a car loan, you own the vehicle from settlement. With a novated lease, the financier owns it until the residual is paid.
Novated lease payments come partly from pre-tax salary, so the benefit scales with your marginal tax rate.
A novated lease is a car fringe benefit. FBT is usually calculated using the statutory formula method at 20% of the base value.
Post-tax contributions reduce the taxable value of the benefit. This is how most providers bring the FBT liability down.
Eligible battery electric and hydrogen fuel cell cars can be exempt from FBT, but the exemption is narrow and still reportable.
Every novated lease ends with a residual payment. The ATO sets minimum residual values, and you cannot reduce them with a trade-in.
On a car loan, compare the comparison rate, not the advertised rate. It folds the fees into one figure.
Which Option Suits Your Situation?
Your employment status decides this more often than the car does. This table covers the eight most common situations.
Your Situation | Usually Better Suited To | Why |
|---|---|---|
Salaried employee, employer offers packaging | Novated lease | Pre-tax payments and bundled running costs are only available through an employer |
Salaried employee, employer does not offer it | Car loan | Without your employer agreeing to novate, the structure is not available to you |
Self-employed or sole trader | Car loan | A novated lease needs an employer to take on the lease obligation. Ask your accountant about business finance instead |
Casual, contract or short tenure | Car loan | The lease obligation returns to you if the job ends, which can be costly mid-term |
Buying an eligible electric car | Price both carefully | The FBT exemption can change the numbers, but only for eligible vehicles under the threshold |
Want to own the car from day one | Car loan | Ownership transfers at settlement rather than after a residual payment |
Plan to keep the car long-term | Car loan | No residual to refinance and no lease to re-novate when circumstances change |
Want one predictable deduction | Novated lease | Fuel, servicing, tyres, registration and insurance can be bundled into the one payment |
Novated Lease vs Car Loan: The Key Differences
The difference is who owns the car and where the money comes from. Everything else follows from those two facts.
Novated lease
Three-way agreement with your employer
Paid from pre-tax and post-tax salary
Financier owns the car during the term
Running costs can be bundled in
Creates an FBT liability
Ends with a residual payment
Car loan
Two-party agreement with a lender
Repaid from your take-home pay
You own the car from settlement
Running costs are budgeted separately
No FBT and no employer involved
Ends when the final repayment clears
Feature | Novated Lease | Car Loan |
|---|---|---|
Who is involved | You, your employer and a financier | You and a lender |
Employment needed | Yes. The arrangement ends if the job does | No |
Payment source | Pre-tax and post-tax salary | Post-tax income |
Vehicle ownership | Financier, until the residual is paid | You, from settlement |
Running costs | Can be bundled into the payment | Paid separately as they arise |
Tax treatment | Car fringe benefit. FBT applies unless exempt | No FBT. Interest may be deductible for business use |
End of term | Pay the residual, refinance or sell | Loan closes, or a balloon falls due if you chose one |
Changing jobs | Obligation returns to you until re-novated | No effect. The loan is yours either way |
Credit assessment | Applies through the financier | Applies through the lender |
How a Novated Lease Works
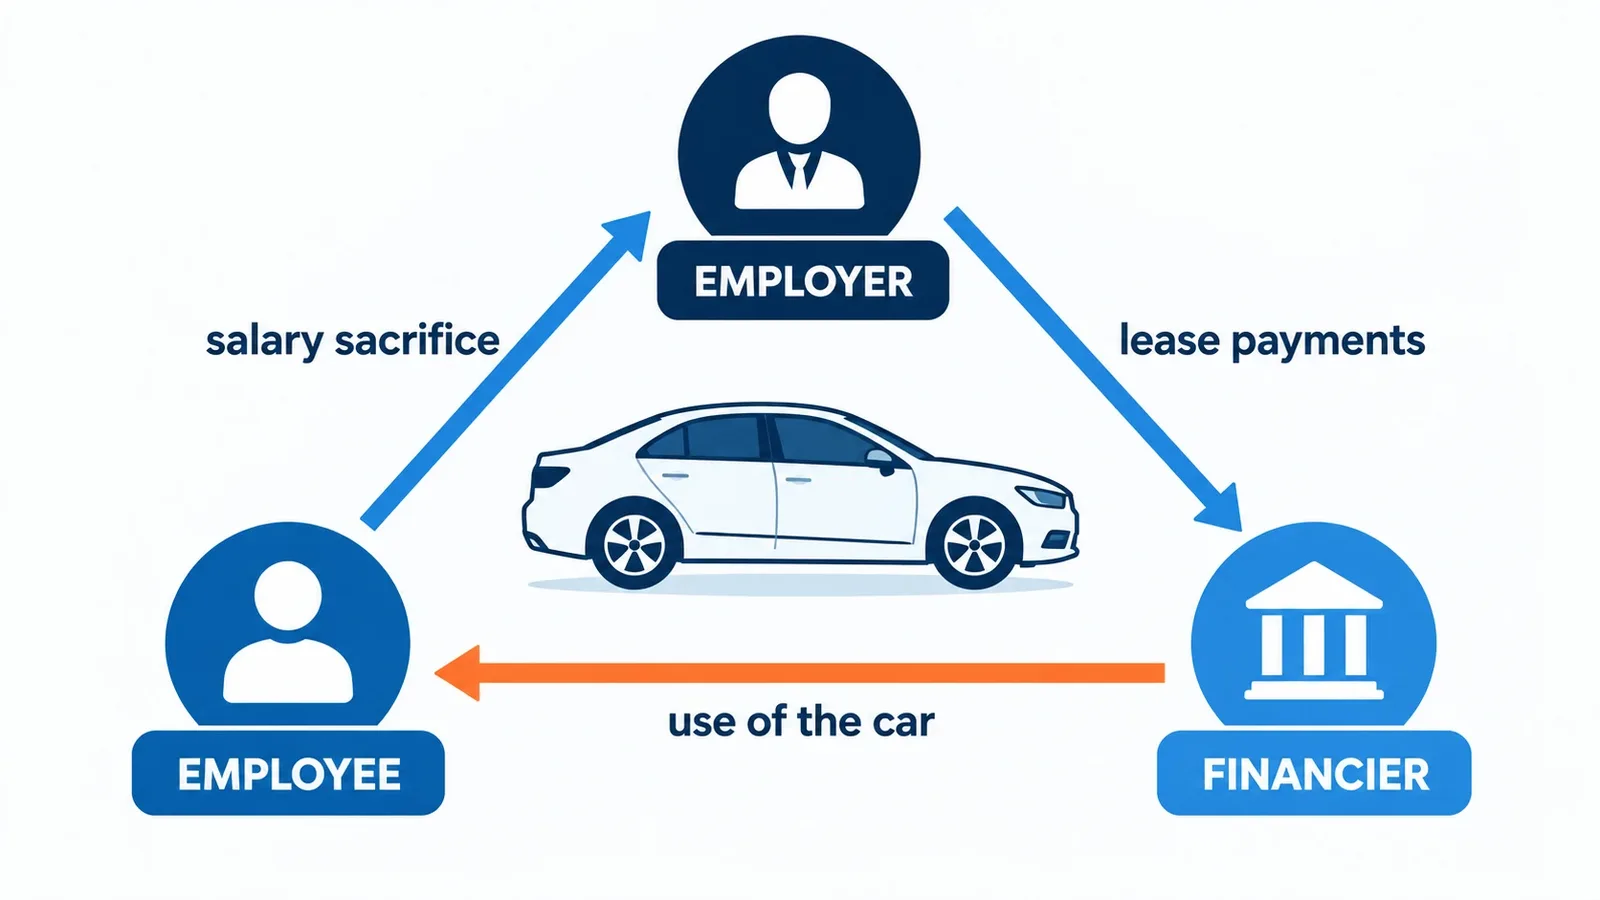
Your employer agrees to take on your lease payments and deduct them from your salary. The financier buys the car and owns it. You drive it.
Party | What They Do | What They Hold |
|---|---|---|
You, the employee | Choose and drive the car. Agree to sacrifice part of your salary to cover the payments | Use of the vehicle |
Your employer | Takes on the lease obligation and makes the payments through payroll | The lease obligation, while you are employed |
The financier | Buys the vehicle and collects the lease payments | Legal ownership, until the residual is paid |
Because the financier buys the car, you still choose the vehicle yourself. Most providers ask you to nominate one and will want the purchase to go through a licensed motor car trader. Confirm your provider’s requirements before you commit to a car.
Tip: the pre-tax benefit scales with your marginal tax rate. A higher marginal rate means a larger reduction in taxable income for the same payment. That is why two people on the same car can see very different numbers. A registered tax agent can model it against your actual income.
What FBT Means for You
A car provided under a novated lease is a car fringe benefit. FBT is usually worked out using the statutory formula method, which applies a statutory percentage of 20% to the base value of the car.
Term in the ATO Formula | What It Is |
|---|---|
A | The base value of the car |
B | The statutory percentage, which is 20% |
C | The days the car was available for private use |
D | The total days in the FBT year |
E | The employee contribution, which reduces the taxable value |
The ATO formula is (A × B × C ÷ D) - E. That final term is why a novated lease quote shows two deduction lines rather than one. Providers split your payments between pre-tax and post-tax so the post-tax portion can reduce the taxable value.
The Electric Car FBT Exemption
Eligible battery electric and hydrogen fuel cell cars can be exempt from FBT, but the conditions are narrow and plug-in hybrids no longer qualify.
Condition | What the ATO Requires |
|---|---|
Vehicle type | A zero or low emissions vehicle. Battery electric and hydrogen fuel cell cars qualify. Motorcycles and scooters do not |
Design | Designed to carry a load of less than one tonne and fewer than nine passengers |
First use | First held and used on or after 1 July 2022 |
Luxury car tax | LCT has never applied to the importation or sale of the vehicle |
Plug-in hybrids | Not a zero or low emissions vehicle under FBT law from 1 April 2025. Transitional provisions apply in limited cases |
Still reportable | The employer must still work out a notional taxable value and may need to report it |
The luxury car tax threshold for fuel-efficient vehicles is $91,661 for the 2026 to 2027 financial year. The threshold for other vehicles is $80,809.
Warning: an FBT exemption is not the same as an invisible benefit. Even when the car is exempt from FBT, the benefit can still appear as a reportable fringe benefit on your income statement. That figure is used in tests for things such as family assistance and some government levies and surcharges. Ask your employer what will be reported before you sign.
Residual Value: What You Owe at the End
Every novated lease finishes with a residual payment. It is set at the start; it is not optional, and the ATO sets a minimum for each lease term.
ATO Requirement | What It Means |
|---|---|
Minimum residual per term | The residual must be no less than the published minimum for that lease term |
Reasonable estimate | It must reflect a reasonable estimate of the market value at the end of the lease |
Longer term, lower residual | More years means more depreciation, so the minimum falls as the term lengthens |
No reduction from trade-ins | The residual cannot be reduced by a trade-in or a cash contribution from you |
Payable regardless of value | It falls due whether or not the car is worth that much on the day |
You have four options when the term ends.
Option | What It Means |
|---|---|
Pay the residual | You take ownership of the car outright |
Refinance the residual | A new lease or loan covers the amount, with new interest costs |
Sell the car | Proceeds cover the residual. A shortfall is yours to pay; a surplus is usually yours to keep |
Trade in and re-lease | Start a new lease on a different vehicle, subject to your employer and provider |
Ask your provider for the exact residual in dollars, not just a percentage, and check it against what you expect the car to be worth on that date.
How a Car Loan Works
You borrow a set amount, own the car from settlement, and repay the lender from your take-home pay. The structure is simpler, and the whole cost sits in one place.
Feature | Secured Car Loan | Unsecured Loan |
|---|---|---|
Security | The vehicle is security for the loan | No security over the vehicle |
On default | The lender can repossess the car | The lender cannot repossess the car |
Interest rate | Usually lower, because the lender carries less risk | Often higher |
Insurance | Comprehensive cover is usually required | Usually at your discretion |
Read the Comparison Rate, Not the Headline Rate
The comparison rate is a single figure for the cost of a loan that includes the interest rate and the fees.
Compare like with like. A comparison rate is only meaningful against the same loan amount and the same term, so line the quotes up before you judge them.
Warning: fees vary more than rates do. ASIC reviewed more than 350,000 car loans and found large differences in the fees consumers paid. A broker, a dealership and a lender can each charge separately on the same deal. Ask for every fee in writing before you sign.
Balloon Payments
A balloon payment lowers your regular repayment by deferring a lump sum to the end of the loan. It does not lower the total cost.
Moneysmart is direct about this: you pay interest on the deferred amount, so the total cost of the loan is generally higher. Choose one only if you are confident you will have the money when it falls due.
A balloon on a car loan and a residual on a novated lease create the same practical problem at the same moment. A large payment arrives at the end of the term, and the car may be worth less than the amount owed.
What Happens If Your Job Changes?
This is the single biggest risk a novated lease carries and the clearest advantage a car loan has.
If You | Novated Lease | Car Loan |
|---|---|---|
Change employers | The lease must be re-novated to the new employer, or the obligation returns to you | No effect |
Employer will not novate | You cover the payments from post-tax income and lose the tax treatment | No effect |
Are made redundant | Payments continue and fall back to you | No effect |
Take unpaid leave | Salary deductions stop, so arrangements must be made with your employer and provider | Repayments continue as normal |
Want to exit early | Early termination costs apply and are set by the lease | Early payout figures apply, and some loans allow extra repayments |
Can You Use Either One on a Used Car?
Yes to both, with conditions. Car loans for used vehicles are widely available, and many novated lease providers will fund a used car within their own age and condition limits.
Check | Novated Lease | Car Loan |
|---|---|---|
Vehicle age limit | Set by the provider and financier, usually measured at the end of the lease | Set by the lender, usually measured at purchase |
Who sets the rule | The provider, not tax law, so limits vary between providers | The lender, so limits vary between lenders |
Amount funded | The financier buys the vehicle outright | Lenders may fund a lower proportion of the price on an older car |
Where you can buy | Most providers require a licensed motor car trader | Dealer or private sale, depending on the lender |
Whichever route you take, a licensed motor car trader gives you consumer protections that a private sale does not. Ask for any age limits in writing before you shortlist a car.
Tip: sort the funding before you fall in love with a car. Knowing your approved amount, the age limits that apply, and the fees involved narrows the shortlist before you start looking. It also means you are comparing cars you can actually fund.
Costs to Compare Beyond the Repayment
Compare the total cost over the full term. A weekly figure hides the fees, the final payment and the running costs.
Cost | Novated Lease | Car Loan |
|---|---|---|
Establishment or application fee | Charged by the financier or provider | Charged by the lender |
Ongoing account or management fee | Often charged monthly by the provider | Varies by lender |
Interest | Built into the lease payment | Shown as the interest rate and comparison rate |
Running costs | Bundled if you choose a fully maintained lease | Budgeted and paid by you |
Final payment | Residual, set at the start | Balloon, only if you chose one |
Early exit | Termination costs set by the lease | Payout figure, sometimes with a fee |
Insurance | Usually required and often bundled | Comprehensive cover usually required by a secured lender |
Buying the Car at J & V Elite Motors
Whichever way you fund it, you still have to choose the vehicle. That part does not change.
J & V Elite Motors has sold used vehicles from Hammond Road in Dandenong since 2003, which is more than 20 years in the same location. The dealership is family-operated, holds motor car trader licence LMCT 9914, pre-inspects its vehicle stock through a licensed VicRoads auto repair shop, and runs its own service centre for customers after the sale. It is also an approved Australian Warranty Network Dealer, and trade-ins are accepted.
The dealership assists with car finance enquiries. It does not arrange novated leases or salary packaging, which are set up through your employer and a salary packaging provider. If you are arranging a novated lease elsewhere, your provider can still purchase a vehicle from the dealership once you have nominated it.
Finance options may be available, subject to application, eligibility, lender criteria and approval. Warranty options may be available. Ask J & V Elite Motors about coverage for the vehicle you are considering. Buyers across Noble Park, Springvale, Keysborough and Mulgrave are within a short drive of the Dandenong dealership.
Browse the current used vehicle listings, start a car finance enquiry, or contact the team to book an inspection and test drive.
Frequently Asked Questions
What Is the Difference Between a Novated Lease and a Car Loan?
A novated lease is a three-way agreement between you, your employer and a financier, funded from a mix of pre-tax and post-tax salary, with the financier owning the car until you pay the residual. A car loan is a two-party agreement between you and a lender, repaid from your take-home pay, and you own the car from settlement.
Is a Novated Lease Cheaper Than a Car Loan?
Not automatically. The pre-tax component reduces your taxable income, and the size of that benefit depends on your marginal tax rate. Against that sit FBT, lease fees, management fees and a residual payment at the end. The only reliable comparison is the total cost over the full term. A registered tax agent can model it against your actual income.
Do I Own the Car With a Novated Lease?
Not during the lease. The financier holds legal ownership for the term. You take ownership once you pay the residual at the end. With a car loan, ownership passes to you at settlement, although a secured lender can repossess the vehicle if you default.
What Happens to a Novated Lease If I Change Jobs?
The lease does not end. It must be re-novated to your new employer if they agree to take it on. If they do not, the obligation returns to you, and you cover the payments from post-tax income, losing the tax treatment that made the arrangement attractive. Check the exit and re-novation terms before you sign.
Can I Get a Novated Lease If I Am Self-Employed?
Generally no. A novated lease requires an employer to take on the lease obligation through payroll. Sole traders and contractors without an employer cannot novate a lease. Speak to your accountant about the finance structures that do suit a business.
What Is a Residual Value and Do I Have to Pay It?
The residual is the amount owing at the end of the lease. It is set at the start, and it is not optional. The ATO requires it to be at least the published minimum for the lease term and to reflect a reasonable estimate of the market value at the end. You can pay it, refinance it, or sell the car and use the proceeds, but a shortfall is yours to cover.
What Is a Comparison Rate and Why Does It Matter?
A comparison rate is a single figure for the cost of a loan that includes the interest rate and the fees. It matters because a low advertised rate can carry high fees. Compare rates only across the same loan amount and the same term, or the comparison is meaningless.
Can You Novated Lease or Finance a Used Car?
Yes to both. Car loans for used vehicles are widely available, and many novated lease providers fund used cars within their own age and condition limits, usually based on the age at the end of the lease. Those limits come from the provider and financier rather than from tax law, so ask for them in writing.